Chat on WhatsApp

UK Tax and Accounting

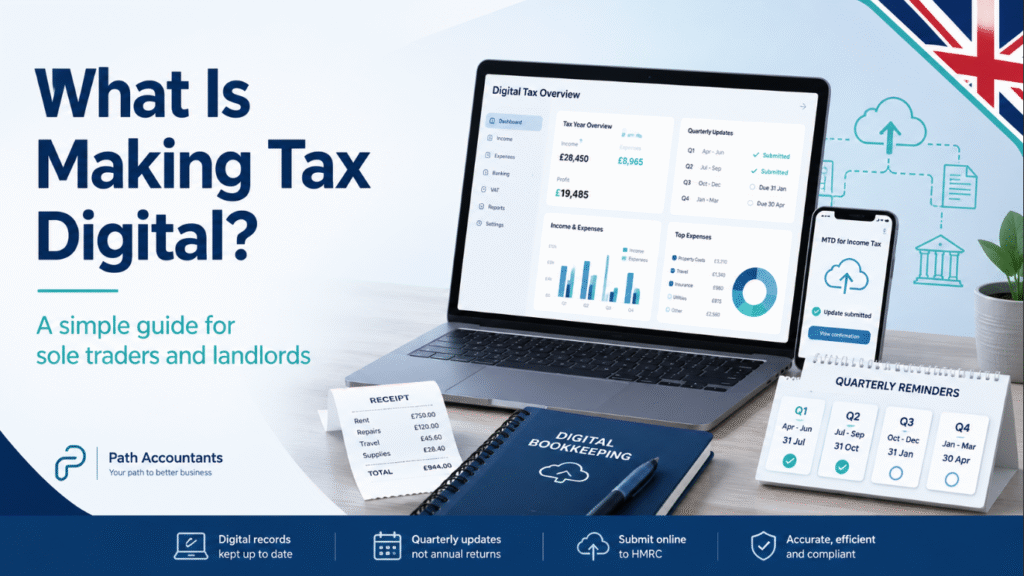
What is Making Tax Digital guide showing digital tax records, quarterly updates, bookkeeping software, and HMRC online submission for UK sole traders and landlords
UK Tax and Accounting

What Is Making Tax Digital? MTD Rules Explained

Making Tax Digital (MTD) is a HMRC’s system for keeping tax records digitally and sending tax updates through compatible software. For Income Tax, it affects sole traders and landlords with qualifying income over £50,000 from April 2026, over £30,000 from April 2027, and over £20,000 from April 2028. In simple words, Making Tax Digital means tax will no longer be something you only sort once a year. If MTD applies to you, you will usually keep digital records, send four quarterly updates, and submit one final tax return. What actually changes under Making Tax Digital? The biggest change is the routine. Instead of collecting receipts, bank statements, rent records, and invoices near the Self Assessment tax return deadline, you need to keep your records updated during the year. Main changes include: This is why what is Making Tax Digital is not just a software question. It changes how regularly you organise your records. Who needs to use Making Tax Digital? Making Tax Digital already applies to VAT registered businesses. HMRC says VAT registered businesses must use compatible software to keep VAT records and file VAT returns. For Income Tax, the rules mainly apply to sole traders and landlords with self employment income, property income, or both. Start date Who needs to use MTD for Income Tax 6 April 2026 Sole traders and landlords with qualifying income over £50,000 6 April 2027 Sole traders and landlords with qualifying income over £30,000 6 April 2028 Sole traders and landlords with qualifying income over £20,000 If you are VAT registered, also check Path’s guides on VAT and the VAT threshold. What counts as qualifying income? Qualifying income usually means your gross income before expenses. This is where many people get confused because they check profit instead of total income. For example, if you receive £28,000 in rental income and £25,000 from self employment, your qualifying income is £53,000. Even if your profit is much lower after costs, you may still fall into Making Tax Digital. Check these situations carefully: This is one of the most important parts of what is Making Tax Digital, because being under the threshold by profit does not always mean you are under it by gross income. Making Tax Digital deadlines The first Income Tax group starts on 6 April 2026. HMRC lists the standard quarterly update deadlines as 7 August, 7 November, 7 February, and 7 May. Date What happens 6 April 2026 Start keeping digital records if MTD applies 7 August 2026 First quarterly update deadline 7 November 2026 Second quarterly update deadline 7 February 2027 Third quarterly update deadline 7 May 2027 Fourth quarterly update deadline 31 January 2028 Final MTD tax return and tax payment deadline for 2026 to 2027 You can also read Path’s guide on the tax return deadline for wider Self Assessment dates. What records and software do you need? You need digital records for the income and expenses covered by Making Tax Digital. For sole traders, this may include sales, invoices, purchases, travel, software, phone costs, equipment, and bank charges. For landlords, it may include rent, repairs, letting agent fees, insurance, service charges, and property finance costs. The record should explain the transaction clearly. “£500 expense” is weak. “£500 boiler repair for rental property, paid on 12 May, invoice saved” is much better. You also need software that works with Making Tax Digital. HMRC says compatible software should support digital records and quarterly updates. Your options usually include: If you are choosing software, Path’s guide on the best accounting software for sole traders is a useful next read. Can you still use spreadsheets? Yes, but spreadsheets must fit the MTD process. A spreadsheet alone may not be enough if it cannot connect to HMRC through compatible or bridging software. Spreadsheets can work if you update them regularly, keep clear entries, save receipts, and avoid mixing personal and business costs. They become risky when you only update them once a year. The real question is not only “Can I use spreadsheets?” It is whether your spreadsheet is strong enough for quarterly reporting. Does Making Tax Digital mean paying tax four times a year? No. Quarterly updates do not mean quarterly Income Tax payments. The updates show income and expenses during the year. Your final payment deadline remains linked to the final tax return. For the first MTD Income Tax year, the final return and payment deadline is 31 January 2028. MTD can still help with cash flow because updated records give you a clearer view of your likely tax bill. You can also use Path’s UK income tax calculator or self employed calculator. What happens if you miss a deadline? HMRC has said there will be no penalties for missing quarterly update deadlines in the 2026 to 2027 tax year, but you still need to keep digital records and send the updates before submitting your final return. Penalties can still apply for late tax returns, late payments, and poor records. The first year may be more forgiving, but it is still better to build the right habit from the start. To reduce problems: How MTD affects landlords and sole traders Landlords need to watch their rental income carefully because property income counts towards the MTD threshold. This matters if you have more than one property, jointly owned property, letting agent deductions, repairs, service charges, or finance costs. Path’s guide on tax and rental income may also help. Sole traders need a cleaner system for income and expenses. Payments may come through bank transfer, cash, card machines, Stripe, PayPal, or invoices. Costs may be paid from different cards or accounts. Under MTD, that loose system becomes harder to manage. A simple monthly routine helps: For better record keeping, read Path’s guides on bookkeeping for sole traders and small business bookkeeping. How Path Accountants can help with Making Tax Digital If you are still unsure what is Making Tax Digital means for your business or rental income, Path Accountants can help you understand
How to Calculate Goodwill in Accounting
UK Tax and Accounting

How to Calculate Goodwill in Accounting for a Business Purchase

To calculate goodwill in accounting, you take the price paid for a business and compare it with the fair value of the assets and liabilities that come with it. If the buyer pays more than the fair value of the identifiable net assets, that excess is goodwill. Under IFRS 3, the acquirer recognises identifiable assets, liabilities, and any non controlling interest separately from goodwill, then records the remaining excess as goodwill or, in some cases, a bargain purchase gain. Goodwill shows the value of things a buyer wants but cannot always touch or list line by line. That may include a strong reputation, loyal customers, skilled staff, a trusted brand, or a business model that already works. ACCA’s guidance on goodwill describes goodwill as future economic benefits from assets acquired in a business combination that are not individually identified and separately recognised. What goodwill in accounting means Goodwill is an intangible asset created during a business acquisition. It does not usually appear because a business simply trades well for a few years. It appears when one business buys another and pays more than the fair value of the identifiable net assets acquired. IFRS 3 requires identifiable assets and liabilities to be recognised separately from goodwill, which is why goodwill becomes the remaining balance after that work is done. This is why two businesses with similar equipment and similar stock can still sell for very different amounts. One may have better customer retention, stronger margins, a better name in the market, or systems that make future profits more likely. Buyers often pay for that advantage because it saves time, reduces risk, and gives them a stronger position from day one. You can think of goodwill as the value built over time. A business does not become more attractive only because it owns assets. It becomes more attractive because customers trust it, suppliers work well with it, and its reputation makes future income more dependable. That part is harder to measure, but it still carries real value. Why goodwill matters when buying a business Goodwill matters because purchase prices often make little sense without it. A buyer may look at a target company and see modest cash, stock, and equipment, yet still pay a much higher figure. That does not always mean the buyer has overpaid. It often means the business has qualities that are expected to earn money well after the deal closes. This happens often in service firms, consultancies, agencies, medical practices, contractor businesses, and companies with repeat clients. In those cases, the main value may sit less in physical assets and more in relationships, contracts, brand recognition, and a stable flow of work. Once a business owner moves from routine compliance into buying or selling a company, the discussion shifts from yearly reporting to what the business is really worth. How to calculate goodwill in accounting The method to calculate goodwill in accounting follows a clear order. Start with the price paid for the business This is the total consideration transferred by the buyer. It may be cash, shares, deferred payments, or contingent consideration in more complex deals. IFRS 3 sets out that the acquirer measures the business combination using the acquisition method and recognises the consideration, the acquired net assets, and the resulting goodwill or bargain purchase gain. Identify the assets acquired The next step is to identify what the buyer has actually acquired. That may include cash, receivables, stock, equipment, property, customer lists, licences, patents, or other separately identifiable intangible assets. IFRS 3 requires identifiable assets acquired to be recognised separately from goodwill. Measure those assets at fair value This is where many mistakes happen. The book values in the seller’s old accounts may not match fair value at the acquisition date. A building may be worth more than its carrying amount. Stock may be worth less. A customer relationship may need a separate valuation. If the fair values are wrong, the goodwill figure will also be wrong. Identify and measure the liabilities Liabilities matter just as much as assets. Loans, trade payables, lease obligations, tax liabilities, and other obligations reduce the net value of the acquired business. IFRS 3 requires liabilities assumed to be recognised and measured as part of the business combination accounting. Work out the identifiable net assets Once the identifiable assets and liabilities are measured, the net assets are simply the fair value of assets less the fair value of liabilities. That gives the amount the buyer has acquired before goodwill is considered. Record the excess as goodwill If the buyer paid more than that identifiable net asset amount, the excess becomes goodwill. That is the core process used to calculate goodwill in accounting. ACCA’s IFRS 3 guidance also sets out the same broad approach in acquisition accounting, including the treatment of non controlling interests in more advanced cases. Example of how to calculate goodwill in accounting A buyer acquires a company for eight hundred thousand pounds. The acquired business has assets with a fair value of three hundred and fifty thousand pounds. Those assets include cash, stock, equipment, and a separately valued customer relationship. The liabilities come to one hundred thousand pounds. That means the fair value of the identifiable net assets is two hundred and fifty thousand pounds. The buyer paid eight hundred thousand pounds, so the remaining five hundred and fifty thousand pounds is goodwill. In this example, the buyer did not pay that extra amount by accident. They may have paid for a recognised brand, long standing client relationships, a stable team, or confidence in future earnings. That is how most people first understand how to calculate goodwill in accounting in a business setting. What usually sits inside goodwill Goodwill often reflects value such as: The IFRS Foundation has noted that part of the premium paid in acquisitions may relate to benefits such as synergies and an assembled workforce, even when those items are not recognised separately as identifiable assets on acquisition. What should not be left inside

Debtors vs Creditors
UK Tax and Accounting

What is the Difference Between a Creditor and a Debtor?

Debtors are the people who owe you money, while creditors are the people you owe money to. That’s the basic idea. But in real business life, especially in the UK, it goes much deeper than that. These two terms directly affect your cash flow, your profit, and even whether your business survives tough months. If you’re running a business or even thinking about it, understanding how this ties into things like small business accounting is essential. Why Debtors vs Creditors Matters A lot of business owners hear these terms and assume they’re just accounting jargon. But honestly, understanding debtors vs creditors can be the difference between: Here’s why it matters: Even profitable businesses fail simply because they don’t manage this balance properly. What Is a Creditor? A creditor is any person or organisation that you owe money to. This usually happens when someone provides you with goods, services, or a loan and allows you to pay later instead of upfront. Example: Until you pay them, they are your creditor. Types of Creditors Most UK businesses deal with two main types: 1. Loan Creditors These are lenders like: For example, if you take out funding to grow your business or switch from sole trader to limited company, the lender becomes your creditor. 2. Trade Creditors These are suppliers or service providers who give you goods or services on credit. Examples include: If you’re outsourcing payroll through a service like payroll services, they may become your creditor until you settle invoices. Being a Creditor Yourself Here’s something many people don’t realise. Depending on your business model, you can also become a creditor. If you: Then you are the creditor, and your client becomes the debtor. What Is a Debtor? A debtor is someone who owes money to another person or business. In simple terms, it’s the opposite of a creditor. Example: That client is your debtor until the payment is made. Types of Debtors In business, you’ll usually come across: 1. Trade Debtors These are your customers who: This is common if you provide services like bookkeeping for sole traders or consulting. 2. Loan Debtors These include individuals or businesses who: 3. Staff Loans (Less Common) Some companies give small loans to employees. In that case, the employee becomes a debtor. Debtors vs Creditors Key Differences Aspect Debtors Creditors Meaning Owe money to your business You owe money to them Role Customer or borrower Supplier or lender Cash Flow Impact Brings money in Takes money out Accounting Treatment Asset Liability Example Unpaid invoice Supplier bill How Debtors vs Creditors Work Together In real life, businesses are almost always both. You’re rarely just one or the other. Imagine this: So: Your job is to manage timing properly so you don’t run out of cash. Debtors and Creditors in Small Business Accounting This is where debtors vs creditors becomes really important. On Your Balance Sheet If you’re unsure how these appear in real accounts, it’s worth understanding the basics of small business bookkeeping. How They Affect Your Business Assets and Liabilities Cash Flow Late payments from debtors can delay: You can also check current limits like the VAT threshold to understand when obligations kick in. Why Balance Is Everything Too many debtors (unpaid invoices) can leave you stuck. Too many creditors (debts) can overwhelm your finances. The goal is to find a balance where: Debtors vs Creditors Together How They Differ A business owner in the UK: At that moment: At the same time: So you can be both at once. How Debtors vs Creditors Affects Cash Flow Cash flow is where most businesses struggle. Here’s the truth: Profit doesn’t mean cash in the bank. You might have: If those debtors delay payment, you could struggle to: That’s why managing debtors vs creditors is critical. Common Mistakes Businesses Make Most small businesses get this wrong at some point. 1. Not Following Up on Debtors They send invoices… and just wait. No reminders, no follow-ups. 2. Giving Long Payment Terms Offering 60+ days without thinking about cash flow impact. 3. Paying Creditors Late This damages relationships and can lead to penalties. 4. Relying Too Much on Credit Using loans or credit cards without proper planning. How to Manage Debtors Properly If you want smoother cash flow, start here. Many businesses also work with professionals such as accountants in London to manage debtor tracking efficiently. How to Manage Creditors Smartly Handling creditors well can actually help your business grow. When Debtors Become Risky Debtors are not always a good thing. They become risky when: In serious cases, businesses may need: When Creditors Become a Problem Creditors can also cause trouble if not managed well. Watch out for: This can quickly damage your financial health. Our Case Insight Let’s compare two businesses: Business A Business B Even if both earn the same, Business A will be far more stable. That’s the real impact of managing debtors vs creditors properly. Debtors vs Creditors in Everyday Life This isn’t just business. You see it daily: Same concept, just different scale. Why Getting Professional Help Matters Managing debtors vs creditors sounds simple, but doing it properly requires structure. At Path Accountants, businesses get support with: You can also book a consultation if you want help reviewing your numbers. Conclusion Once you understand debtors vs creditors, business finances start to feel much clearer. It all comes down to one simple idea: The businesses that succeed are the ones that manage both sides carefully. FAQs

Turnover vs Revenue the Key Difference Many UK Businesses Miss
UK Tax and Accounting

Turnover vs Revenue the Key Difference Many UK Businesses Miss

If you’ve ever looked at a company’s accounts or read a financial report, you’ve probably come across the terms turnover and revenue. Many people assume they mean exactly the same thing, but that’s not always the case. Understanding turnover vs revenue is important for business owners, freelancers, and anyone trying to make sense of financial performance. In simple terms, revenue is the total money a business earns from its main activities, while turnover can sometimes refer to revenue but may also describe how quickly a business replaces assets like stock or employees. In the UK, however, the word turnover is very commonly used to describe total sales. If you run a small business, manage accounts, or are preparing your tax return through the HMRC self-assessment process, understanding the difference between these two terms can make financial reports much easier to interpret. What Is Revenue? Revenue is the total income a business generates from selling goods or services before any expenses are deducted. It is often called the “top line” in financial reports because it appears at the top of the income statement. For example, imagine a freelance designer in London who earns £5,000 in a month from client work. That £5,000 is the business revenue for that period. Revenue does not include business costs such as: Those expenses are deducted later when calculating profit. Many small businesses track revenue carefully as part of their small business accounting process to understand how much money the business is bringing in each month. Example of Revenue in a Small Business Let’s take a simple example. Item Amount Monthly sales £18,000 Business expenses £10,000 In this case: Revenue simply represents total income before costs are removed. What Is Turnover? Turnover is one of those business terms that can mean slightly different things depending on the context. In the UK, turnover usually refers to the total value of sales made by a business during a specific period. In this sense, turnover and revenue often mean the same thing. However, turnover can also refer to how frequently something changes within a business. Examples include: This is why discussions around turnover vs revenue can sometimes create confusion. Turnover as Sales When HMRC or accountants refer to annual turnover, they normally mean total sales before expenses. For example: A consulting business earns: The business therefore has £250,000 annual turnover. This figure represents total sales before costs. HMRC often uses turnover when determining business obligations such as the VAT registration threshold, which businesses must monitor carefully. You can also see the official explanation of turnover on the UK Government VAT guidance. Turnover vs Revenue: The Key Difference The difference between turnover vs revenue mainly comes down to how the terms are used. In most UK business discussions: However, turnover can sometimes describe other operational metrics. Here’s a simple comparison. Feature Revenue Turnover Meaning Total income from business activities Often used to describe sales Used in financial statements Yes Usually informal or contextual Used globally Yes More common in the UK Other meanings Rare Can refer to employee or inventory turnover So when comparing turnover vs revenue, revenue is always income, while turnover can have multiple meanings depending on context. Why Businesses Use the Word “Turnover” Many business owners prefer using the word turnover instead of revenue. This is mainly because the term is widely used in tax discussions and financial planning. For example: A business owner filing a SA100 self-assessment tax return may need to report turnover figures as part of their financial reporting. Turnover also helps business owners quickly communicate the scale of their operations. Examples: These figures quickly show the size of the business. How Turnover vs Revenue Differs To understand turnover vs revenue more clearly, let’s look at a practical example. Imagine a small online retailer selling handmade products. During the year the business earns: Total income = £170,000 In this situation: However, if we measure inventory turnover, we are looking at how quickly stock is sold and replaced. Example: Inventory turnover = 6 times per year This demonstrates why the discussion around turnover vs revenue depends on context. Different Types of Turnover in Business Turnover can refer to different operational metrics within a business. Here are the most common types. Sales Turnover Sales turnover is simply the total value of goods or services sold during a period. Many small businesses track sales turnover alongside their bookkeeping records to understand performance. Example: A café earns £7,000 weekly. Annual sales turnover would be roughly £364,000. Inventory Turnover Inventory turnover measures how quickly stock is sold and replaced. Businesses with high inventory turnover usually operate efficiently. Industries where this metric matters include: Employee Turnover Employee turnover measures how frequently staff leave a company and are replaced. High employee turnover can indicate: Companies aim to keep employee turnover low to maintain stability. Asset Turnover Asset turnover measures how efficiently a business uses its assets to generate revenue. Manufacturing companies often track this to evaluate equipment productivity. Why Understanding Turnover vs Revenue Matters Understanding turnover vs revenue is more than just learning financial terminology. It helps business owners: For example, if you are running a small company and planning your corporation tax obligations, understanding how revenue and turnover appear in financial records is essential. It also helps businesses monitor financial performance through tools like: Turnover vs Revenue in Financial Statements In official accounting documents, the term revenue is normally used instead of turnover. A typical financial statement may include: However, business owners often use turnover in casual discussions. For example: “Our turnover this year reached £1.2 million.” Both statements refer to the same idea: total sales income before expenses. If you’re unsure how these figures affect your business, it may be worth speaking with professional accountants in London who can help interpret your financial data. Common Misunderstandings About Turnover and Revenue Many new business owners misunderstand turnover vs revenue, which can lead to confusion. Here are some common misconceptions. Turnover Means Profit This is incorrect. A business may have

5 Best Accounting Software for Sole Traders in UK
UK Tax and Accounting

5 Best Accounting Software for Sole Traders

The best accounting software for sole trader businesses in the UK is one that is simple, HMRC-compliant, affordable, and designed specifically for small businesses not large corporations. For most sole traders, QuickBooks, Xero, or FreeAgent tend to be the strongest choices because they balance ease of use with proper UK tax compliance. But the real answer depends on your situation. Whether you’re VAT registered, newly self-employed, or planning to grow into a limited company will affect what works best for you. Why Sole Traders Can’t Rely on Spreadsheets Anymore Many sole traders start with spreadsheets. It feels manageable in the beginning. But once you: things become more complex. Spreadsheets don’t automatically calculate VAT. They don’t sync bank transactions. And they don’t protect you from small errors that can lead to penalties. That’s where choosing the best accounting software for sole trader businesses becomes important. It’s not about fancy features it’s about compliance, clarity, and saving time. What Should the Best Accounting Software for Sole Trader Include? Before comparing brands, here’s what actually matters. 1. MTD Compliance If you are VAT registered, you must keep digital records and submit returns electronically. The software must connect directly with HMRC. If you’re unsure whether you need to register yet, read our full guide on the VAT threshold in the UK. 2. Automatic Bank Feeds Manual entry creates errors. The best accounting software for sole trader setups syncs directly with your bank and categorises transactions automatically. This alone can save 4–6 hours every month. 3. Clear Tax Estimates As a sole trader, you file your return using the SA100 tax return form under Self Assessment. Good software estimates your tax liability in advance so you’re not surprised in January. You can also check important dates using our HMRC tax deadline calendar. 4. Simple Reporting You should easily see: Without needing accounting training. Top Software Options for Sole Traders in the UK QuickBooks – Best for Beginners QuickBooks is extremely popular among UK sole traders. Why? If you’re newly self-employed and recently completed your Self Assessment registration in the UK, QuickBooks can feel very supportive. For many new business owners, it becomes the best accounting software for sole trader needs simply because it reduces confusion. Xero – Best for Growing Sole Traders Xero is slightly more advanced and ideal if your business is expanding. It offers: If you are comparing whether to remain self-employed or incorporate later, our guide on sole trader vs limited company explains when growth might require structural change. Xero works well in both cases, which makes it a strong long-term choice. FreeAgent – Built for UK Freelancers FreeAgent is tailored for UK freelancers and contractors. It provides: If you’re an IT contractor, you may also want to understand how IR35 off payroll working rules impact your tax position. In many freelance scenarios, FreeAgent becomes the best accounting software for sole trader businesses because it feels designed specifically for UK tax rules. Sage – Established and Reliable Sage is trusted and widely recognised. It handles: If you also manage employees and need to understand payroll terms, see our guide on what is a payroll number and what is PAYE. KashFlow – Budget-Friendly Option KashFlow is practical and affordable. It supports: For sole traders who want compliance without complex features, it works well. Compare self-employed accounting software Software Best For MTD Ready Ease of Use Starting Price QuickBooks Beginners Yes Very Easy ~£12 Xero Growing businesses Yes Moderate ~£14 FreeAgent Freelancers Yes Easy ~£19 Sage Traditional setups Yes Moderate ~£15 KashFlow Budget users Yes Easy ~£8 How Path Accountants Help You Choose the Right Software Choosing the best accounting software for sole trader businesses isn’t just about features it’s about choosing something that matches your tax position and growth plans. At Path Accountants, we don’t randomly recommend software. We look at: For example: We also offer: Many sole traders install software but configure it incorrectly. VAT settings are wrong. Expense categories are misaligned. Bank feeds aren’t properly reconciled. We make sure your system is structured correctly from day one. Software is just a tool. Proper setup makes it powerful. What happens if I ignore proper bookkeeping? Poor records can trigger issues such as: Good software reduces risk. Conclusion The best accounting software for sole trader businesses in the UK is the one that: For beginners, QuickBooks works well.For long-term scalability, Xero is powerful.For freelancers, FreeAgent feels tailored. But software alone isn’t enough. Proper advice, correct setup, and ongoing support make the real difference. If you want help choosing or setting up the right system, you can book a consultation here. Because when your accounting is organised, your business becomes easier to manage. FAQs

Bookkeeping for sole traders
UK Tax and Accounting

Bookkeeping for Sole Traders: A Practical UK Guide for 2026/27

Bookkeeping for sole traders means keeping an accurate record of the money coming into and going out of your business. For a self-employed person, those records are what eventually support the income, expenses and profit reported to HMRC. They can also help you understand whether the business is actually making money, what tax may be coming up and whether you are approaching VAT or Making Tax Digital thresholds. The rules have become more important in 2026/27 because Making Tax Digital for Income Tax is now mandatory for some sole traders. This guide explains what records a sole trader should keep, how to organise bookkeeping, cash basis versus traditional accounting, allowable expenses, VAT, bookkeeping software and the new MTD for Income Tax requirements. Sole Trader Bookkeeping at a Glance Question Quick answer Do sole traders need bookkeeping records? Yes. You need records that support the figures included in your Self Assessment tax return. How long should records be kept? Normally at least 5 years after the 31 January submission deadline for the relevant tax year. Do you need a business bank account? Not necessarily, although separating business and personal transactions can make bookkeeping much easier. Check what your bank allows. Is bookkeeping software compulsory? Not for every sole trader. However, compatible software is required where Making Tax Digital for Income Tax applies, and separate digital-record rules apply to most VAT-registered businesses. When does MTD for Income Tax apply? From April 2026 for qualifying income over £50,000, with lower thresholds being introduced in 2027 and 2028. Is cash basis still available? Yes. Cash basis has been the default accounting method for most eligible self-employed businesses since the 2024/25 tax year. What Is Bookkeeping for a Sole Trader? Sole trader bookkeeping is the process of recording and organising the financial transactions connected with your self-employed business. That normally includes: You do not normally send all of these records to HMRC with your tax return. Instead, you keep them so you can calculate your business profit or loss accurately and show how you arrived at the figures reported if HMRC asks for supporting records. Bookkeeping also provides the starting point for wider small business accounting, tax preparation and financial reporting. Why Bookkeeping Matters for Sole Traders It is easy to think of bookkeeping as something that only matters when your Self Assessment deadline approaches. In practice, leaving everything until January can create much bigger problems. Receipts disappear, business and personal spending becomes difficult to separate, expenses are forgotten and it becomes harder to remember what individual transactions were for. Keeping the books up to date can help you: It also gives you more useful information during the year instead of discovering how the business performed months after the year has finished. What Bookkeeping Records Must a Sole Trader Keep? HMRC requires self-employed people to keep records of business income and expenses for Self Assessment. Typical records include: Sales and business income Keep evidence of the money the business earns, including: Your bookkeeping should make it possible to trace the income recorded back to the underlying transaction. Business expenses Keep records of costs you believe relate to running the business. Depending on the business, these might include: Not every cost paid from a business account automatically qualifies as an allowable tax expense. Where a cost has both personal and business use, only the appropriate business element may be relevant. Receipts and supporting evidence Keep the documents supporting the transactions recorded in your books. Examples include: HMRC’s record-keeping guidance for self-employed businesses explains the core records that should be retained. How Long Do Sole Traders Need to Keep Bookkeeping Records? For Self Assessment, records normally need to be kept for at least 5 years after the 31 January submission deadline for the relevant tax year. For example, if the filing deadline for a return is 31 January 2027, the supporting records would normally need to be retained until at least the end of January 2032. Different rules can apply in particular circumstances, including very late returns. Digital storage can make this considerably easier. Receipts and invoices can be attached to individual bookkeeping transactions rather than stored in boxes that have to be searched through years later. How to Do Bookkeeping as a Sole Trader A simple sole trader bookkeeping system does not need dozens of spreadsheets or complicated accounting processes. The important part is consistency. 1. Separate Business and Personal Transactions A sole trader is not legally separate from their business in the same way as a limited company. That does not mean mixing every personal and business transaction together is a good bookkeeping system. Using a dedicated account for business transactions can make it easier to: A sole trader does not necessarily have to open a business bank account purely because they are self-employed, although you should check the terms of your bank account to make sure business use is permitted. 2. Record All Business Income Your bookkeeping should capture all business income, not only the payments that are easiest to see in your main bank account. That could include: The date on which income is recorded for tax purposes can depend on the accounting method you use. For most eligible sole traders using cash basis, income is generally recorded when the money is actually received. Under traditional accounting, the timing can be different. 3. Record Business Expenses Properly Do not wait until the tax return is being prepared to work out what individual payments were for. Record the expense when it happens and give it a clear category. For example: £49.00 — accounting software subscription — software is much more useful six months later than: £49.00 — card payment Keep the supporting receipt or invoice with the transaction wherever possible. 4. Keep Track of Business Mileage If you use a vehicle for business journeys, maintain the information needed to support the business mileage being claimed. A mileage record might contain: Sole traders may be able to use simplified expenses for qualifying vehicle mileage

Small Business Accounting
UK Tax and Accounting

What Is Small Business Accounting and Why Does It Matter in the UK?

Small business accounting is the process of recording income, tracking expenses, managing taxes, and keeping financial records accurate so a business can operate legally and profitably. For UK small businesses, good accounting is not just about numbers. It affects cash flow, tax bills, growth decisions, and even whether the business survives long term. If you run a small business, accounting is not optional. It is the backbone of every financial decision you make. How small business accounting works? Small business accounting covers all the financial tasks needed to run a business in the UK while staying compliant with the rules set by HM Revenue and Customs. This includes. Unlike large companies, small businesses often manage these tasks with limited time and resources, which is why clear systems matter. Why small business accounting is so important Good small business accounting helps you. Without accurate records, you are guessing rather than managing. What small business accounting includes Bookkeeping Bookkeeping is the day to day recording of transactions. This includes sales, purchases, expenses, and payments. If bookkeeping is wrong, everything else is wrong. Learn more about professional bookkeeping for small businesses. Tax compliance and returns Small business accounting ensures you meet all tax obligations, including. Missing deadlines or submitting incorrect figures can lead to penalties. Keeping track of key dates using the HMRC tax deadline calendar can help. Cash flow management Accounting helps you track. This prevents situations where a business looks profitable on paper but struggles to pay expenses. Small business accounting for different business types Sole traders Sole traders must keep accurate records of income and expenses and submit a Self Assessment tax return each year. If you are new, registering early is essential. Limited companies Limited companies have stricter accounting requirements. These include. Accounting errors here can affect both the company and directors personally. Common small business accounting mistakes Good accounting systems prevent these issues before they cause damage. Do small businesses need an accountant Many small businesses start without an accountant, but most successful ones eventually use professional support. An accountant helps with. If you are searching locally, working with a small business accountant near you can provide tailored advice. Accounting software and small businesses Software helps with. However, software still requires correct setup and regular review to be effective. How Path Accountants supports small business accounting Path Accountants works with UK small businesses at every stage, from startups to growing companies. We support clients with bookkeeping, tax compliance, payroll, VAT, and long term financial planning. Our focus is on clear advice, accurate records, and helping business owners understand their numbers, not just file reports. If you want tailored support, you can book a free consultation. Conclusion Small business accounting is not just a legal requirement. It is a tool that helps you understand your business, protect your cash flow, and plan for the future. With the right systems and support in place, accounting becomes a strength rather than a burden, allowing you to focus on growing your business with confidence. FAQs

Tax Return Deadline
UK Tax and Accounting

UK Tax Return Deadlines 2026/27: Self Assessment Dates You Need to Know

The main tax return deadline in the UK is 31 January 2027 for online Self Assessment returns covering the 2025/26 tax year. Any Self Assessment tax due for 2025/26 is generally payable by the same date. There are several important dates before and after January, including the 5 October 2026 Self Assessment registration deadline, the 31 October 2026 paper tax return deadline, the 30 December 2026 PAYE coding deadline, and the 31 July 2027 second payment on account deadline. If you are preparing a return for income earned between 6 April 2025 and 5 April 2026, these are the dates you need to know. Important: The 31 January 2027 deadline relates to the 2025/26 tax year. A Self Assessment return covering the actual 2026/27 tax year, ending 5 April 2027, would normally have an online filing deadline of 31 January 2028. For other business and personal tax dates throughout the year, see our HMRC tax deadline calendar. Quick answer: next Self Assessment deadlines Deadline What it is for 5 October 2026 Register for Self Assessment if required for the 2025/26 tax year 31 October 2026 Submit a 2025/26 paper Self Assessment tax return 30 December 2026 Submit online if you want eligible tax of less than £3,000 collected through PAYE 31 January 2027 Submit your 2025/26 online tax return 31 January 2027 Pay your 2025/26 balancing payment and, where applicable, first payment on account 31 July 2027 Make your second payment on account where required For most taxpayers filing online, 31 January 2027 is the date that matters most. However, waiting until January to start preparing the return can create problems if records are missing, figures need reconciling or you discover that you need additional information. 5 October 2026: Self Assessment registration deadline If you need to complete a Self Assessment return for the 2025/26 tax year and have not already registered, you generally need to tell HMRC by 5 October 2026. This can apply if, for example, you became self-employed, started receiving income that needs to be reported through Self Assessment or otherwise became liable to file. HMRC states that you should tell them by 5 October if you need to complete a return for the previous tax year and either: If you register after 5 October 2026, HMRC may provide a different filing deadline based on when they notify you. However, this does not necessarily move the tax payment deadline. Tax due for 2025/26 can still need to be paid by 31 January 2027. If you have recently become a sole trader, getting registered early also gives you more time to organise your records and understand what income and expenses need to be reported. 31 October 2026: paper tax return deadline If you are submitting a paper Self Assessment tax return for 2025/26, HMRC must normally receive it by 11:59pm on 31 October 2026. This deadline is three months earlier than the online filing deadline. If you miss the paper filing deadline, do not simply send a late paper return without checking your position. In many cases, filing online before the January deadline may be the better route. Most taxpayers now complete their Self Assessment returns online, which provides additional time to prepare and submit the return. 30 December 2026: PAYE coding option There is another useful Self Assessment deadline that is often overlooked. If you owe less than £3,000 through Self Assessment and already pay tax through PAYE, HMRC may be able to collect the amount through your PAYE tax code instead of requiring it as a separate lump-sum payment. To potentially use this option, your online tax return must normally be submitted by 11:59pm on 30 December 2026. You must also meet HMRC’s other eligibility conditions. In particular: Submitting before 30 December does not guarantee that coding will be possible, but missing the deadline means you will generally need to use another payment method. 31 January 2027: online tax return deadline The main Self Assessment deadline for 2027 is 11:59pm on 31 January 2027. This is the deadline for filing your 2025/26 online Self Assessment tax return. The return covers income and gains arising during the tax year from 6 April 2025 to 5 April 2026. Depending on your circumstances, the return can include: You do not need to wait until January to file. A 2025/26 return can be submitted after the tax year ends, once you have the information needed to prepare it accurately. Filing earlier can also give you more time to understand the size of the tax bill rather than discovering the amount shortly before payment is due. If you want professional support with the return, see our Self Assessment tax return accountant in London service. 31 January 2027: Self Assessment tax payment deadline The filing deadline and payment deadline fall on the same date for most online Self Assessment taxpayers. Any balancing payment for the 2025/26 tax year is normally due by 11:59pm on 31 January 2027. You may also need to make your first payment on account for 2026/27 on the same date. This means the amount payable in January can sometimes be significantly higher than the final tax balance for the year just ended. For example, someone may need to pay: 2025/26 balancing payment plus first payment on account towards 2026/27 This is one reason it is useful to calculate your likely position well before January. If you are self-employed and want an early indication of your Income Tax and National Insurance position, use our self-employed tax calculator. 31 July 2027: second payment on account deadline If you are required to make payments on account, the second instalment for 2026/27 will normally be due by 31 July 2027. Payments on account are advance payments towards your next Self Assessment bill. Each payment is normally based on half of the relevant previous year’s tax liability, with: Payments on account are generally not required where your previous year’s relevant Self Assessment tax liability was less than £1,000, or where more than

Why i received HMRC Savings Tax Letter
UK Tax and Accounting

HMRC Savings Tax Letters : Why You Receive Them and What to Do Next

HMRC savings tax letters are notices sent by HMRC to tell you that you may have paid too much or too little tax on your savings interest. These letters usually arrive when banks or building societies report interest you earned and HMRC notices a difference between what tax was due and what was paid. Although they can feel worrying at first most savings tax letters are routine and easy to deal with once you understand them. What HMRC savings tax letters are HMRC savings tax letters are official letters explaining how your savings interest has been taxed. Since banks no longer deduct tax automatically HMRC now checks savings interest data itself and updates your tax record where needed. These letters usually explain They are not penalty notices and do not mean you have done anything wrong. You can also see how savings income fits into your wider tax position in our guide to UK income tax Why HMRC sends savings tax letters Banks and building societies report savings interest directly to HMRC. If this information does not match your PAYE or tax record HMRC sends a savings tax letter to correct the difference. Common reasons include This is why many people receive HMRC savings tax letters even when their finances seem straightforward. Official HMRC guidance on savings interest How savings interest is taxed in the UK Savings interest is taxed depending on your income tax band and your personal savings allowance. Most people have a tax free allowance Once you earn more than your allowance the extra interest becomes taxable. If you are unsure which tax band you fall into you can check our guide Types of HMRC savings tax letters you may receive Not all savings tax letters mean the same thing. HMRC uses different letters depending on your situation. You may receive a letter saying Some letters are for information only while others ask you to respond. What to do when you receive an HMRC savings tax letter Do not ignore the letter. Take a few minutes to review it carefully. You should If everything is correct HMRC will usually deal with it automatically. If something looks wrong you should contact HMRC. If the letter links to PAYE adjustments our guide on PAYE may help What happens if you owe tax on savings interest If HMRC says you owe tax there are usually two outcomes. For smaller amounts HMRC adjusts your tax code so the tax is collected gradually through PAYE.For larger amounts HMRC may ask for a direct payment or include it in self assessment. This is why many people see their tax code change after receiving a savings tax letter. You can also learn how HMRC handles underpaid tax in our guide What happens if you are due a refund If HMRC finds that you overpaid tax on savings interest they usually issue a refund automatically. Refunds may be In most cases you do not need to apply unless HMRC asks for confirmation. Do HMRC savings tax letters mean you need self assessment Not always. Many people assume they must file a tax return after receiving a savings tax letter but this is often not the case. You may need self assessment if Otherwise PAYE adjustments usually cover savings tax. If you are unsure you can review Common mistakes people make with savings tax letters People often panic or make avoidable mistakes. Common errors include A calm review usually prevents bigger problems later. How to reduce future HMRC savings tax letters You cannot always avoid savings tax letters but you can reduce how often they occur. Helpful steps include Better planning leads to fewer surprises. How Path Accountants can help with HMRC savings tax letters At Path Accountants we help individuals review HMRC savings tax letters check interest figures and correct tax codes where needed. We also advise on tax efficient saving so you minimise future issues. Our team can You can request a free consultation here View our full tax services Conclusion HMRC savings tax letters are usually routine checks rather than cause for concern. They exist to make sure the right amount of tax is paid on savings interest. By reviewing the figures responding on time and keeping your tax record up to date you can handle these letters with confidence. Understanding how savings tax works puts you in control and helps prevent repeat letters in the future. FAQs

Small Business Bookkeeping in Uk
UK Tax and Accounting

Small Business Bookkeeping : A Guide for UK

Small business bookkeeping is the process of recording organising and managing your business finances so you always know where your money is going. It tracks income expenses invoices bills and taxes and helps you stay compliant with HMRC. Good bookkeeping is not just about numbers. It gives you clarity control and confidence to make better business decisions. What small business bookkeeping means Small business bookkeeping means keeping accurate financial records of everything that moves in and out of your business. This includes sales purchases expenses payments and taxes. Bookkeeping creates the foundation for your accounts tax returns and cash flow planning. Without proper bookkeeping it becomes hard to know if your business is profitable or if you can afford to grow. Many small businesses struggle not because they lack customers but because they lose control of their finances. You can also see how bookkeeping fits into the wider tax picture in our guide to UK income tax Why bookkeeping matters for small businesses Bookkeeping keeps your business organised compliant and financially healthy. When bookkeeping is done properly you can Poor bookkeeping often leads to missed expenses late filings and unexpected tax bills. HMRC also legally requires businesses to keep accurate records What bookkeeping includes for a small business Small business bookkeeping usually includes These records support your annual accounts and self assessment filings.If you file tax returns you may also want to read Bookkeeping example for a small business Imagine a small marketing agency invoicing clients monthly while paying for software rent and freelancers. Without bookkeeping the owner relies on bank balance alone which gives a false picture. With proper bookkeeping the owner can clearly see This allows smarter pricing and better planning. Bookkeeping vs accounting Bookkeeping and accounting are often confused but they are not the same. Bookkeeping focuses on recording and organising financial data regularly.Accounting uses those records to analyse performance prepare accounts and submit tax returns. Bookkeeping comes first. Accounting relies on it. How often small business bookkeeping should be done For most small businesses bookkeeping should be done weekly. Businesses with higher transaction volumes may need daily updates. Leaving bookkeeping until year end often results in missing records errors and higher accounting fees. Common bookkeeping mistakes small businesses make Many small businesses make the same mistakes especially in the early stages. Common issues include These mistakes can lead to HMRC issues and inaccurate tax bills. Manual bookkeeping vs bookkeeping software Some small businesses still use spreadsheets. This can work briefly but becomes risky as the business grows. Bookkeeping software helps by HMRC guidance on digital record keeping Do small businesses need bookkeeping for HMRC Yes. HMRC requires accurate records for all businesses even if you make a loss. With Making Tax Digital rules digital bookkeeping is becoming essential especially for VAT registered businesses. Accurate bookkeeping ensures VAT registered businesses can also review When to outsource small business bookkeeping Many business owners start by doing bookkeeping themselves. Over time it often becomes overwhelming. Outsourcing bookkeeping makes sense when Professional bookkeeping frees you up to focus on growth. How bookkeeping helps small businesses grow Good bookkeeping supports growth by showing what is really happening in your business. It helps you Lenders and investors expect clean accurate records. Small business bookkeeping and tax planning Accurate bookkeeping allows proper tax planning. It helps you Poor bookkeeping almost always leads to rushed returns and missed savings. How Path Accountants support small business bookkeeping At Path Accountants we provide reliable bookkeeping services tailored to small businesses across the UK. We help sole traders limited companies and growing businesses keep accurate records stay compliant with HMRC and gain clear financial insight. Our bookkeeping support includes You can request a free consultation here Explore more services Conclusion Small business bookkeeping is not just an admin task. It is the backbone of a successful business. When your records are accurate and up to date you gain control clarity and confidence. Whether you manage bookkeeping yourself or outsource it the key is consistency. Strong bookkeeping today prevents problems tomorrow and gives your business the foundation it needs to grow. FAQs

Scroll to Top

Book a Free Call

Fill in your details and our team will get back to you shortly

Book Appointment